Debt often carries a negative stigma. But using debt responsibly can be an essential part of a comprehensive financial strategy — and can help you to build wealth.
An Ameriprise financial advisor is prepared to help you understand how your debt fits into your overall financial picture and can affect your financial goals.
As you evaluate your current debts or consider financing a major expense, here are some debt management tips and strategies:
1. Know how much debt you can afford
Managing debt starts with understanding how much borrowing fits comfortably within your budget. Taking on debt that aligns with your income and financial obligations can help you stay on track toward your goals while maintaining flexibility for other priorities.
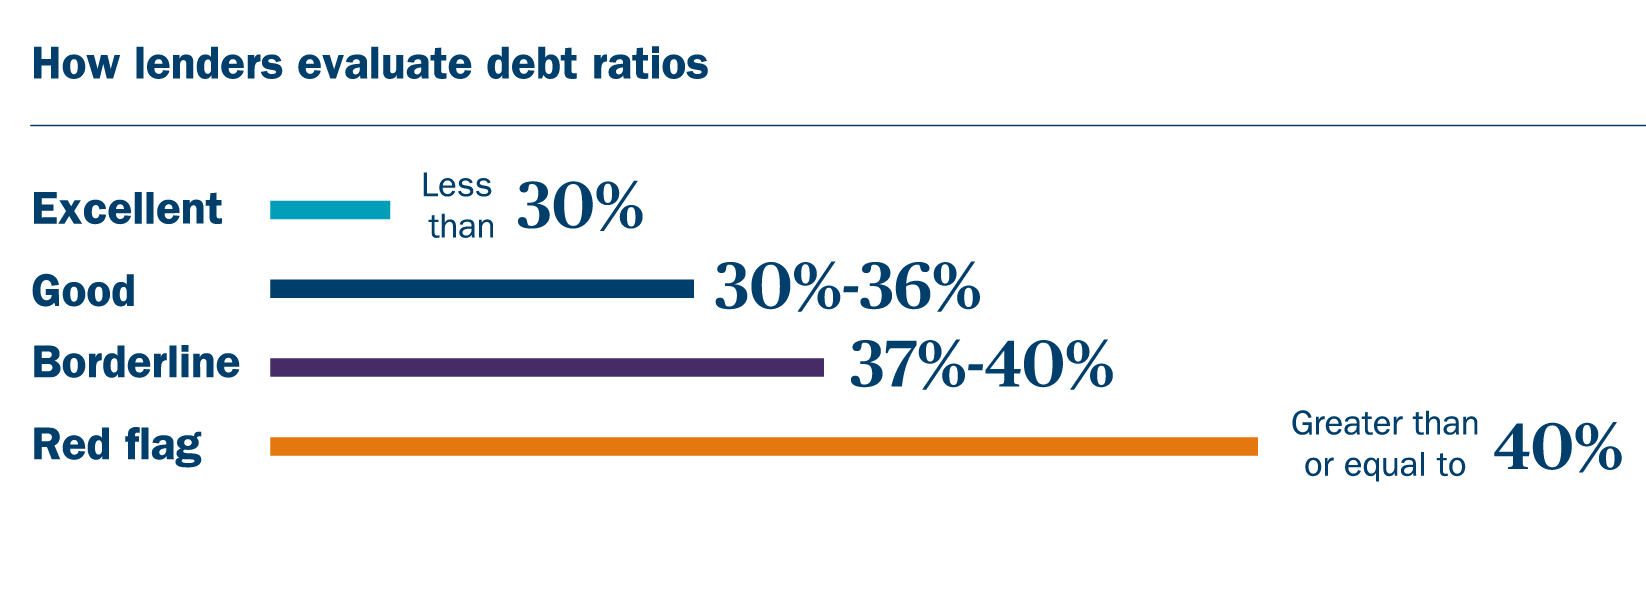
One common way to evaluate affordability is by calculating your debt-to-income (DTI) ratio. To calculate this metric, tally all your minimum monthly debt payments — including your mortgage or rent and student, auto and other loan payments — and divide the total by your pre-tax monthly income. The result, expressed as a percentage, gives a snapshot of how much of your income is already committed to debt repayment.
While there are no absolutes in determining desirable debt-to-income ratios, lenders often use this measure to assess a borrower's ability to manage additional debt. The following general guidelines can help provide context for how your DTI may be viewed by lenders.
2. Understand the difference between good debt and bad debt
Not all debt is created equal. Depending on how it's used, debt can either help support your financial goals or make them harder to achieve. Understanding the distinction can help you make more informed borrowing decisions:
-
“Good” debt is characterized as low-interest debt that helps you increase your income or net worth. Examples include educational loans, a mortgage or a business loan. Debt can also be considered good if it helps you build credit.
-
“Bad” debt is characterized as high-interest debt that is used to purchase depreciating assets. Examples include using credit cards to buy clothing, furniture, or other goods that immediately lose value — then not paying off the balance and building up interest charges.
Ultimately, whether debt is helpful or harmful depends on how much you borrow, the cost of borrowing and how it fits into your overall financial strategy. While some debt can support long-term goals, it's important to manage all debt responsibly and within your means.
Learn more: How to save and pay for a major purchase
3. Be smart about credit cards
Credit cards can offer a host of benefits. They’re convenient. They build a credit history. And they can be a helpful tool for tracking your spending. Most credit cards also provide various security features, including liability protection for fraud or even travel and rental car protection.
For all their benefits, however, credit cards are a less-than-ideal way to borrow money, as they carry high interest rates on any balances you don’t pay off right away.
To avoid those high fees, here are a few debt management tips:
-
Only charge what you can pay off each month.
-
Keep your monthly charges to 20% or less of your maximum credit limit.
-
Always pay your bill on time.
4. Use tried-and-true strategies to pay down debt faster
While paying off debt may seem overwhelming at times, there are practical measures to accelerate your repayment schedule or reduce the amount of interest you’re paying. Loan consolidation, the avalanche method and the snowball strategy are all approaches that can help you tackle debt effectively.
Learn more: Strategies to help pay off debt faster
5. Know when it makes sense to prioritize investing versus paying off debt
The psychological benefits of being debt-free are undeniable. However, if you're behind on your retirement savings or have an especially low interest rate on a mortgage loan, prioritizing debt repayment may not always be the most effective use of additional dollars. In some cases, you may be able to achieve greater long-term value by investing instead. Additionally, certain debts, such as mortgages, home equity loans and student loans, may offer tax benefits, so it's important to consider how they fit into your overall financial picture.
It will depend on your unique situation and goals. For some, the sense of freedom that comes with being debt-free is worth more than the potential returns they might have earned by investing. Reflect on your priorities, run the numbers and be comfortable with any tradeoffs you're making.
Learn more: Is it better to pay off your mortgage or invest?
6. Make sure you have a cash reserve
Even if your priority is paying down your debt, consider setting aside a portion of your monthly income for a cash reserve or emergency fund. This pool of money can act as a cushion, potentially preventing you from getting deeper into debt if you face an unexpected expense.
Learn more: Establishing a cash reserve: How much should you have?
7. Build a budget to manage expenses
A big part of debt management is knowing how to avoid debt. Creating a household budget — and sticking to it — will help you stay on top of debt payments and systematically save for other goals.
Learn more: Personal budgeting strategies to help reach your goals
Balance debt with your other long-term goals
Whether you’re rethinking how to manage your current debts or considering taking on new loans, an Ameriprise financial advisor is prepared to provide personalized advice unique to your situation.
One of your clients has some questions they would like to discuss with you at your next meeting.
warning Something went wrong. Do you want to try reloading? Try again
When you’re ready to reach out to an Ameriprise financial advisor for a complimentary initial consultation, consider bringing these questions to your meeting.
Reach out to %advisor% to start the conversation.
Or, request an appointment online to speak with an advisor.
At Ameriprise, the financial advice we give each of our clients is personalized, based on your goals and no one else's.
If you know someone who could benefit from a conversation, please refer me.
Background and qualification information is available at FINRA's BrokerCheck website.